Filing before the damage is documented
File after the inspection and photos, not before. A claim with no evidence is a claim the adjuster has to guess at.
Your roof is damaged and the claim feels like a second job. Here is the process in plain language — inspection, filing, the adjuster meeting, scope review, payment, and your deductible — and what Bridgegate Construction can and cannot do for you.
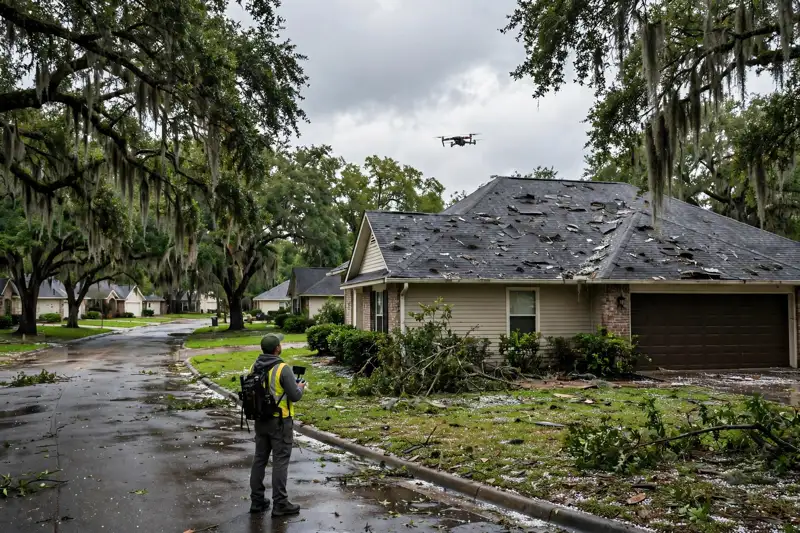
A roof insurance claim has seven steps, and most of the trouble comes from not knowing which one you are on. This page walks through each step — from the inspection to the final payment — and says plainly where a roofing contractor can help and where only your insurer can decide.
Bridgegate Construction LLC is a Houston roofing contractor, not a public adjuster. We inspect your roof, document the damage with photos, and give you a written scope to share with your insurer. We do not negotiate claims, we cannot guarantee approval, and Texas law does not allow a contractor to waive your deductible.
Inspection to payment — what happens at each step, and who decides it.
We inspect the roof, photograph the damage, and record the storm date. Nothing is filed until the damage is documented.
You file the claim with your insurer and get a claim number. Keep the storm date and the photos with your file.
The insurer sends an adjuster to look at the roof. We can be present at your request, with our photos and written scope.
The adjuster writes a scope of what the insurer will pay for. Compare it with our written scope — the two should describe the same roof.
The insurer pays the actual cash value first — replacement cost minus depreciation, minus your deductible. If you have a mortgage, the check may be made out to you and your lender, and the lender endorses it.
With the scope agreed, the repair or replacement is scheduled. The schedule is agreed before work starts.
After the work is completed and documented, recoverable depreciation is paid. You pay your deductible — waiving it is illegal in Texas.
Your insurer also works to a clock. Under Texas Insurance Code Chapter 542 — the Prompt Payment of Claims Act — an insurer must acknowledge your claim within 15 days, accept or reject it within 15 business days (extendable to 45), and pay within 5 business days of accepting it. Late payment can carry 18% interest. These are the insurer's deadlines, not ours, and your policy may add its own — read it, and ask your insurer or adviser if a deadline is unclear.
We inspect the roof, photograph the damage, and record the storm date. Nothing is filed until the damage is documented.
You file the claim with your insurer and get a claim number. Keep the storm date and the photos with your file.
The insurer sends an adjuster to look at the roof. We can be present at your request, with our photos and written scope.
The adjuster writes a scope of what the insurer will pay for. Compare it with our written scope — the two should describe the same roof.
The insurer pays the actual cash value first — replacement cost minus depreciation, minus your deductible. If you have a mortgage, the check may be made out to you and your lender, and the lender endorses it.
With the scope agreed, the repair or replacement is scheduled. The schedule is agreed before work starts.
After the work is completed and documented, recoverable depreciation is paid. You pay your deductible — waiving it is illegal in Texas.
The claim follows the evidence. Keep these together from the first day.
Every damaged slope photographed while the damage is fresh — the record your insurer needs.
The date and type of storm that caused the damage. Your policy and your claim both start from it.
Our written scope of the damage and the work it needs — the document you share with your insurer.
Read your own policy: what it covers, your deductible, and any deadlines it sets. There is no single filing deadline.
What the adjuster saw and wrote down. Compare it with our scope — the two should describe the same roof.
Keep every receipt for the work done. Recoverable depreciation is paid after the work is completed and documented.
Replacement cost minus depreciation, minus your deductible — this is the first payment.
It is not the whole claim. Recoverable depreciation is paid after the work is completed and documented.
The depreciation held back from the first payment.
Paid after the work is done and documented — keep your receipts and invoices.
The amount you pay out of pocket. Wind and hail deductibles are often 1–2% of your dwelling value.
You must pay it. Waiving, rebating, or absorbing a deductible is illegal in Texas.
Most denied or underpaid claims come from mistakes in the first week. These are the ones we see most.
Call (346) 654-5170File after the inspection and photos, not before. A claim with no evidence is a claim the adjuster has to guess at.
There is no single reliable deadline — Texas law, TWIA, and your policy differ. File promptly and read your policy instead of assuming you have two years.
Compare the adjuster’s scope with ours. If they describe different roofs, ask questions before the work starts.
Waiving, rebating, or absorbing a deductible is illegal in Texas. Any contractor offering to cover it is offering to break the law.
Straight talk about where our help ends.
Photos, measurements, and a written scope you can share with your insurer.
At your request, with our photos and written scope in hand.
We do not negotiate claims on your behalf.
Whether a claim is approved, and how much is paid, is your insurer’s decision.
Waiving, rebating, or absorbing a deductible is illegal in Texas.
“Used them for my bodyshop to do some Sheetrock work, ended up using them for my roof and remodel at my house. They gave me deadlines and knocked it out in time. They even helped with all my permits. Manny was here through every step even fought with my insurance company to make sure I get what I was supposed to. Went from business transaction to long time friendship”
Amer ZuriGoogle review · a month ago
✓ Google reviewEvery review quoted on this site is a verbatim Google review of Bridgegate Construction LLC. Read all 31 reviews on our Google profile.
There is no single reliable deadline. Texas law, TWIA, and your own policy set different limits, so file promptly and read your policy instead of assuming you have two years.
Replacement cost value pays the actual cash value first — replacement cost minus depreciation, minus your deductible. Recoverable depreciation is paid after the work is completed and documented. An actual-cash-value-only policy pays the first amount only.
Yes. You must pay your deductible, and waiving, rebating, or absorbing it is illegal in Texas. Wind and hail deductibles are often 1–2% of your dwelling value. Any contractor offering to cover it is offering to break the law.
We can be present at the adjuster inspection at your request, with our photos and written scope. We are not a public adjuster, we do not negotiate claims, and we cannot guarantee approval.
TWIA is the insurer of last resort for the designated catastrophe area — 14 coastal counties, and in Harris County only east of Highway 146, inside La Porte, Morgan’s Point, Pasadena, Seabrook, and Shoreacres. Most of Houston is outside it, and most Houston wind and hail damage falls under a standard homeowners policy.
 Storm Damage Roof RepairFrom lifted shingles to tree-fall, we repair wind and hail damage and document it with photos and a written scope you can share with your insurer.Explore →
 Hail Damage Roof RepairHail bruises shingles and cracks tile in ways you cannot see from the ground. Functional damage generally starts around 1-inch hail — we inspect from the roof surface and document what we find for your adjuster.Explore →
 Roof InspectionA walk of the roof surface covering shingles, flashing, valleys, vents, and ventilation, plus the decking and attic where accessible. You get photos of what we find and a written scope.Explore →Roof Leak RepairWe trace a leak to its source, not the stain on your ceiling — water travels, and the entry point is often far from the drip. Pipe boots, flashing, valleys, and skylight curbs are the usual suspects.Explore →Emergency Roof RepairFor active leaks and storm damage, call (346) 654-5170. We talk through what to do right now to limit the damage, then book an inspection. No same-day promise — just a straight answer and a real plan.Explore →
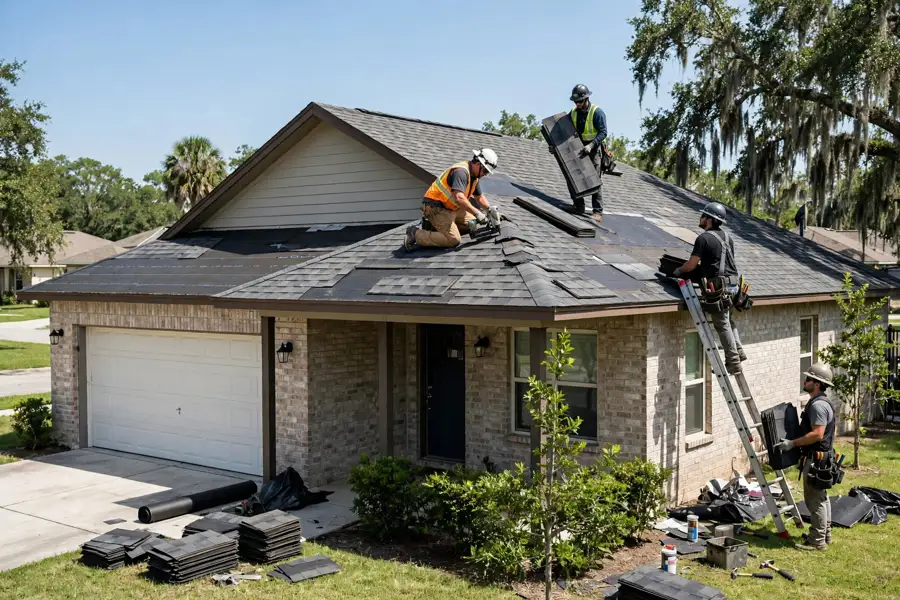 Roof ReplacementA full tear-off to the deck, then new underlayment, flashing, and ventilation, finished with a final walkthrough. Inside Houston, a re-roof needs a Residential Roofing Permit — we help with the permit where one is required.Explore →Roof RepairTargeted fixes for flashing leaks, missing shingles, and punctures. We find the cause before we fix anything, and we tell you plainly when a repair is not enough and replacement is the honest answer.Explore →Roof MaintenanceScheduled checks of flashing, sealant, drainage, and pipe boots — and a clear of valleys and gutters. Catching small problems early is what keeps a Houston roof watertight; check again after hail season.Explore →
Storm damage, a leak, or a roof past its prime? Call Bridgegate Construction LLC at (346) 654-5170 and talk through the next step with a Houston roofing crew. We inspect first, then give you a written scope to approve.
Call (346) 654-5170 →Call (346) 654-5170 or send us a message using the form. Tell us what is happening with your roof and we will talk through the next step, starting with an inspection. Our office hours are Monday to Wednesday, 8 AM–6:30 PM, and Saturday, 9 AM–6:30 PM. We are closed on Sundays.
Claim and inspection guidance on this page follows Texas Department of Insurance advice and FEMA flood-map information. The insurer deadlines above follow Texas Insurance Code Chapter 542 (Prompt Payment of Claims Act). The insurer deadlines above follow Texas Insurance Code Chapter 542 (Prompt Payment of Claims Act).